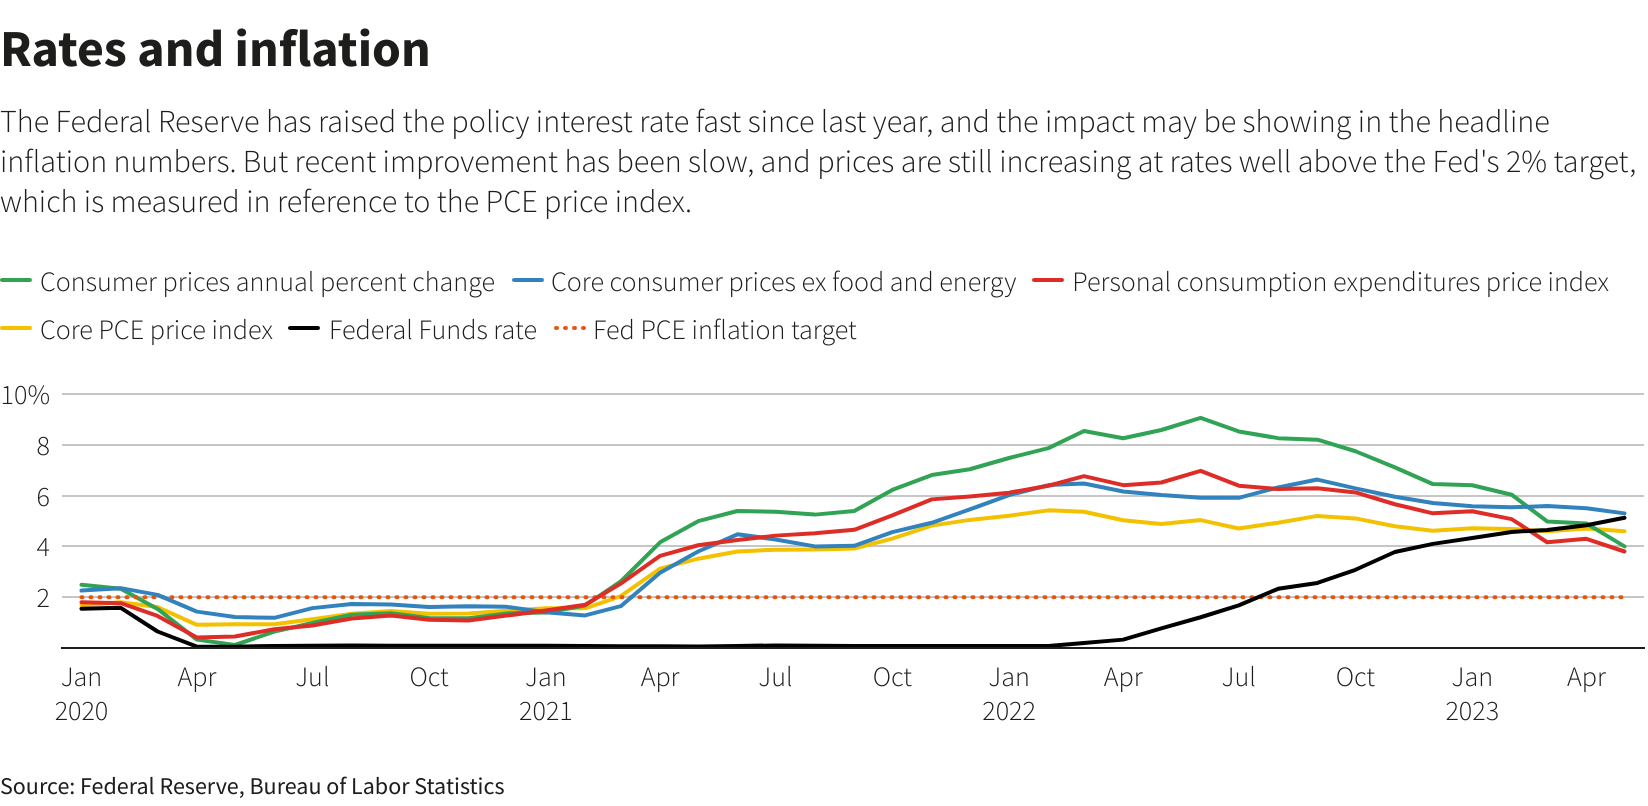
And June's CPI readout should be a marker if the consensus forecast for almost a full percentage-point drop in the headline inflation rate to two year lows of just 3.1% is borne out. Perhaps more important for the Fed, however, is how much the now higher "core" rate of inflation recedes - and that drop is expected to be by a more modest 0.3 point to 5.0%.
Still, encouraged by a screed of other positive disinflation signals this week, U.S. markets are relatively buoyant going into the release and still feel the end of the Fed rate rise campaign is nigh.
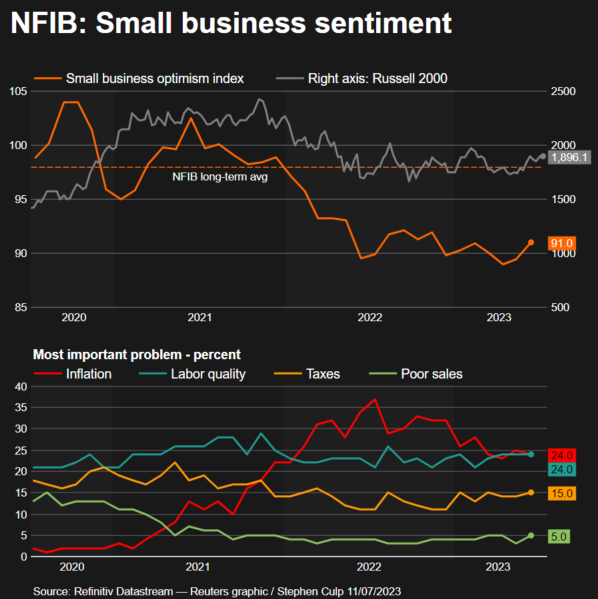
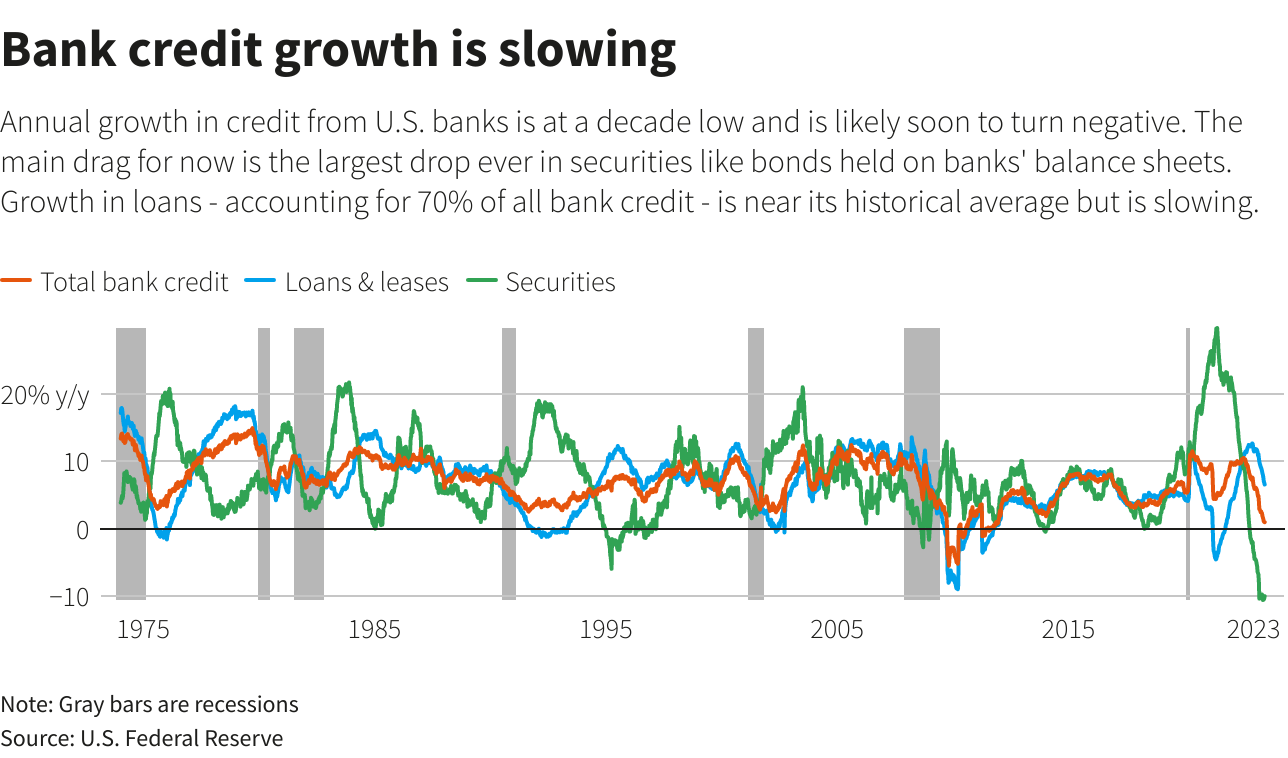
U.S. stocks climbed for the second day in a row on Tuesday and S&P500 futures are positive ahead of today's open - with more signs of rotation in the outperformance of small cap stocks versus the mega cap tech sector, while banks advanced ahead of second-quarter earnings later this week.
Fed futures haven't shifted much, but Treasury bond yields continue to walk back from last week's peaks and volatility there has ebbed a bit - with one eye on a 10-year Treasury auction later in the session.
But the dollar's ongoing slide was most notable.
Alongside thoughts of 'peak Fed', speculation seems to be rising once again that the Bank of Japan will gradually wind-down its super-easy monetary policy stance over the coming months. The dollar/yen exchange rate, now almost 4% down from mid-year peaks, skidded to its lowest in almost a month.
Spurred by aggressive expectations of Bank of England interest hikes far above the Fed's, in order to rein in Britain's outlying inflation problem, the pound briefly hit its highest in 15 months on Wednesday before recoiling. UK bank stocks pushed higher on the rates view and a relatively clean bill of health from Wednesday's financial stability report from the BOE.
Other central banks also gave some cause for applause.
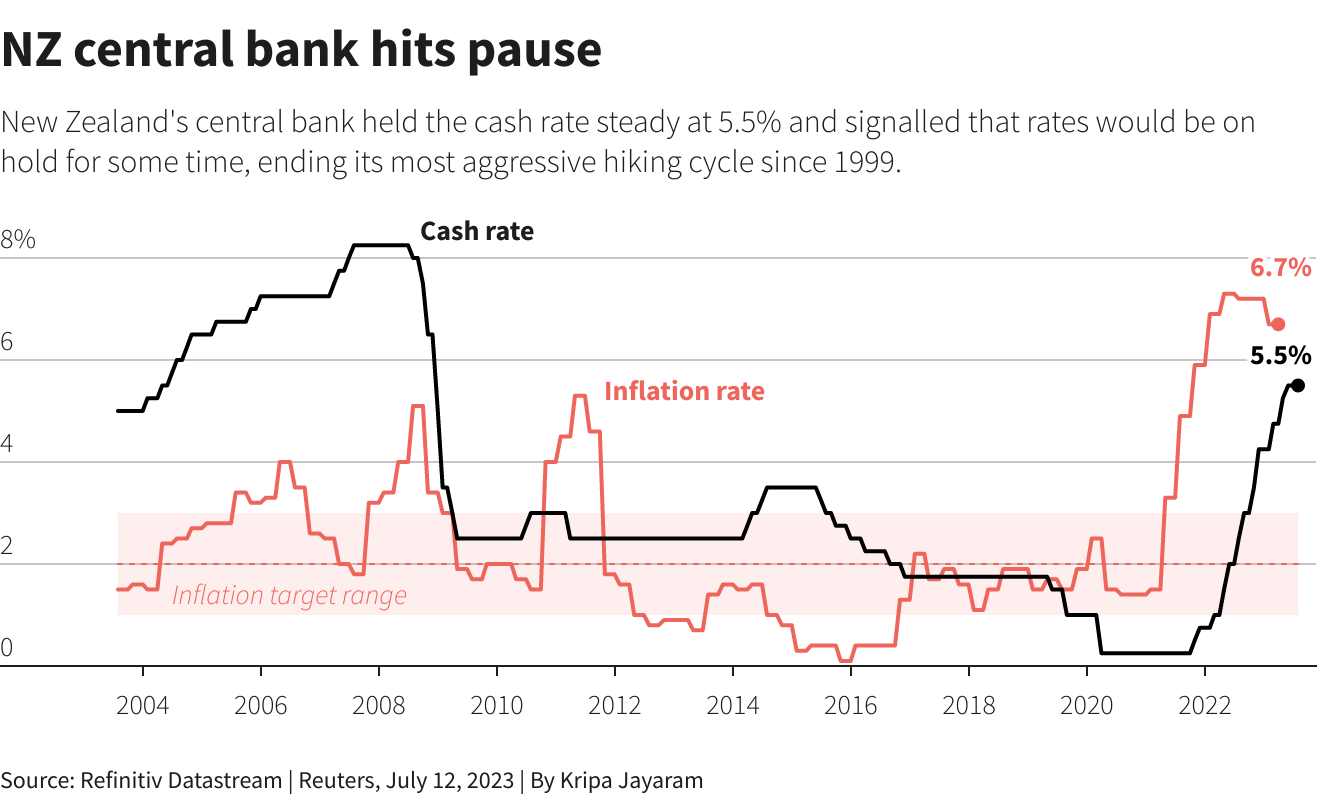
The Reserve Bank of New Zealand paused its long-running rate rise campaign early on Tuesday. And although the Bank of Canada is expected to raise rates another notch later in the day, the decision will be watched closely for hesitation there too.
Elsewhere, Asia bourses were mixed. Japan's Nikkei dialled back amid the sharp yen gains. Shanghai stocks fell, but Hong Kong added more than 1% on this month's optimistic noises about tech sector regulation and upbeat credit data. European indices were up smartly.
The deals world was enlivened as Microsoft cleared major hurdles to its plan to buy videogame maker Activision Blizzard on Tuesday after a U.S. judge gave a thumbs-up to the $69 billion deal and a British regulator suggested it could reconsider its opposition. Activision shares surged 10% and Microsoft shares rose 64 cents to $332.47.